How to Calculate Profit Margins in a Construction Business
Your construction profit margin shows how much of each dollar of revenue remains after the costs included in the calculation. Checking it helps you see whether your prices leave enough to cover overheads and make a profit.
For construction, professional and trades businesses, small estimating errors can affect the result: extra labour, wasted materials, uncharged variations or costs that never made it into the quote.
A useful margin calculation starts with complete, consistent numbers. Here is how to work it out and use the result when you price your next job.
Start with the right revenue and costs
For a completed project, use the revenue earned from that job and the direct costs of delivering the same agreed scope.
Direct costs may include materials, site labour, subcontractors, job-specific equipment hire, delivery and waste disposal. Include relevant employment costs when calculating the cost of labour; the hourly wage alone may understate what the business pays to provide that time.
Your pricing also needs to recognise the cost of your own work. If you are on the tools but take drawings rather than wages, include a realistic allowance for your time in management costing. Keep that allowance identifiable: it is not automatically a deductible wage expense in your accounts.
Calculate the project gross profit margin
For this example, “project gross profit” means revenue less direct job costs, before general business overheads.
Imagine a completed project with revenue of $100,000:
Direct job cost | Amount | |
|---|---|---|
Materials | $35,000 | |
Site labour and related employment costs | $28,000 | |
Subcontractors | $8,000 | |
Job-specific hire, delivery and disposal | $4,000 | |
Total direct job costs | $75,000 |
The calculation is:
Project gross profit = revenue − direct job costs
$100,000 − $75,000 = $25,000
To express that as a percentage:
Project gross profit margin = gross profit ÷ revenue × 100
$25,000 ÷ $100,000 × 100 = 25%
The project has generated 25 cents in gross profit for every dollar of revenue. That amount still needs to contribute towards general overheads and the business’s eventual profit.
These figures illustrate the calculation; they are not a recommended industry target.
Understand the difference between margin and markup
Margin and markup use different starting points.
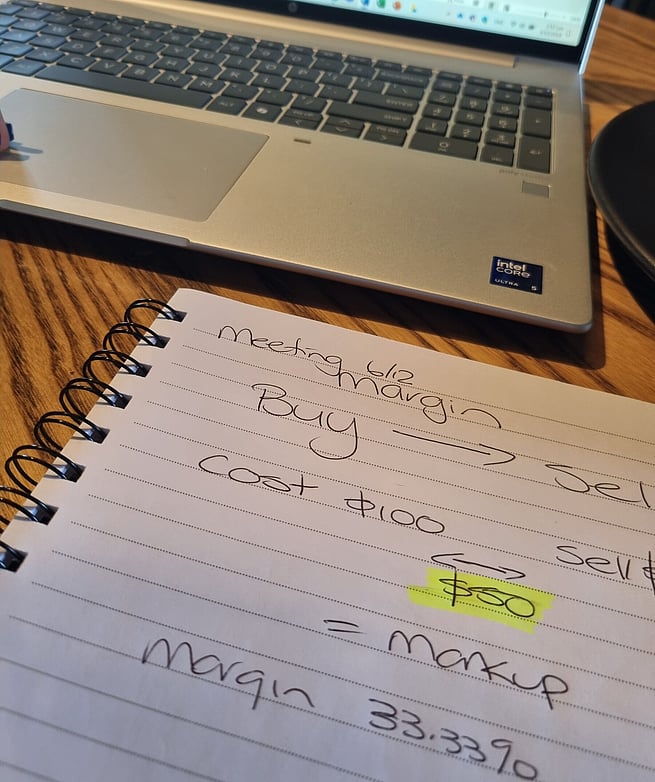
Margin measures profit as a percentage of the selling price. Markup measures the amount added as a percentage of cost.
In the example above:
Markup = $25,000 ÷ $75,000 × 100 = 33.33%
The same job therefore has a 25% margin and a 33.33% markup.
This matters when quoting. Adding 25% to your costs does not produce a 25% margin.
To calculate a price for a target margin, use:
Selling price = estimated direct job costs ÷ (1 − target margin)
If estimated direct costs are $75,000 and the target project gross margin is 30%:
$75,000 ÷ (1 − 0.30) = $107,142.86, excluding GST
This gives the price required for that margin, assuming the estimate holds. You still need to assess whether the quote covers the project’s risks and whether your overall pricing supports your overheads and profit goals.
Check what is left after business overheads
A strong project margin does not automatically mean the business is making a strong net profit.
You also need to cover costs such as administration, office expenses, general insurance, software and other overheads.
For example, across a reporting period, suppose revenue is $500,000 and direct costs are $375,000. Gross profit is $125,000. If operating overheads total $85,000, including relevant depreciation, operating profit is $40,000.
Operating profit margin = $40,000 ÷ $500,000 × 100 = 8%
That is an operating margin before interest and income tax. For an after-tax net margin, use profit after all applicable expenses, including interest and tax, divided by revenue and multiplied by 100.
If you allocate an overhead to jobs for management reporting, make sure you do not subtract it a second time in the same calculation.
Keep checking margins while the job is running
For an unfinished project, costs paid so far do not show the full cost of finishing it.
Update your estimate using costs already incurred plus the remaining cost to complete, including committed purchases and subcontractor work still to come. Compare that with expected revenue for the same scope. Flag unapproved variations separately instead of assuming they will be paid.
Track labour hours, material changes and rework as they happen. After completion, compare the estimate with the actual result and use the differences to improve future quotes.
At Beyond Your Numbers, we help construction and trades business owners understand what their numbers are saying. Contact us to discuss your job margins, pricing and the profitability you want to build.